Abstract:The International Monetary Fund has raised India's FY27 growth forecast to 7%, up 60 basis points from its July estimate, even as retail inflation climbs to 5.5% and the rupee hovers near record lows.
The upgrade, announced in the IMF's October World Economic Outlook, cites strong domestic demand and robust services activity. But the same report warns that higher oil prices and geopolitical tensions could strain the economy.
For Indian traders, the paradox is real: growth is accelerating, yet the currency is sinking and prices are rising. Here's what the numbers mean for your positions.
 Contents
The Numbers Behind the Paradox
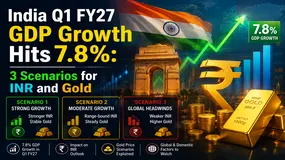
The IMF's upgrade to 7% for FY27 reverses its July downgrade, when it had cut the forecast to 6.4% from 6.5% in April. The Fund also raised its FY28 projection to 7% from 6.7%. On a calendar-year basis, India is expected to grow 7.4% in 2026 and 7% in 2027.
But the headline growth masks a darker side. Retail inflation hit 5.5%, a near two-year high, driven by rising food and fuel costs. The IMF projects inflation to average 5.0% in FY27, up from 2% in FY26, before easing to 4.4% in FY28. The current account deficit is expected to widen to 1.5% of GDP from 0.7% last fiscal.
The rupee is the most immediate pain point. It closed at 96.78 per dollar on Wednesday, its second-weakest close ever, after the RBI's monetary policy failed to boost sentiment. The currency has depreciated 2.03% in FY27 so far, and 5.99% since the US-Iran conflict began in February. The IMF's growth upgrade did little to stem the slide.
Why the Rupee Keeps Falling
The rupee's weakness is not just about the IMF. The RBI's 25 basis point rate hike was already priced in, and the policy statement offered no additional guidance. Dealers say external pressures and weak dollar inflows are driving the currency lower.
Crude oil prices remain elevated due to the Saudi-Houthi conflict, shipping costs, and refinery disruptions. Higher oil imports widen India's trade deficit and put pressure on the rupee. The IMF warns that a prolonged West Asia war could push inflation higher and strain the current account.
Foreign investors are also selling. Rising interest rates in the US and geopolitical uncertainty have prompted consistent outflows from Indian equities. This selling pressure adds to the rupee's woes, making USD/INR an attractive pair for traders betting on further depreciation.
The IMF's Growth Story: What's Behind the Upgrade
The IMF's upgrade is not an isolated achievement.
Several major economies saw upward revisions for 2026, including South Korea (to 3.3% from 1.9%), Germany (to 1.32% from 0.79%), and the UK (to 1.27% from 0.8%). The Fund noted that India stands out with upward revisions, reflecting sustained momentum and growing evidence of stronger growth potential.
But here's the catch: rupee depreciation has reduced India's projected GDP in current dollar terms. The country's global GDP ranking has temporarily slipped to sixth, behind the UK.
Growth in current dollar prices is only about half of the rupee-denominated growth — 4.0% in FY26 and 3.9% in FY27, compared to 7.8% and 7.0% in real terms.
This has implications for the $5 trillion economy target. The rupee's slide has pushed that milestone further away. For traders, this means the rupee's weakness is not just a market blip — it's a structural drag on India's nominal GDP.
How This Affects Your Trades
For USD/INR traders, the trend is clear: the rupee is under pressure. The IMF's growth upgrade does not change the fundamental drivers — oil prices, foreign outflows, and RBI's limited policy room. If crude stays elevated, expect continued depreciation pressure.
Gold and silver slipped on a firm dollar, but the inflation outlook could support bullion in the medium term. With retail inflation at 5.5% and rising, real interest rates remain negative, which is typically supportive for gold.
For equity traders, the growth upgrade is a positive, but the rupee's slide and foreign selling could cap gains. HCLTech rallied after its Q2 results beat expectations, but broader IT stocks may face headwinds from a weak rupee — though a weaker rupee actually boosts IT exporters' margins.
Divergences and Uncertainties
The IMF's inflation forecast of 5.0% for FY27 is lower than the RBI's 5.2% projection. The central bank raised its inflation estimate by 20 basis points last week. This gap suggests the RBI may need to hike rates further if inflation surprises on the upside.
There's also a discrepancy in growth numbers. The RBI earlier this month raised its FY27 GDP forecast to 7.1%, while the World Bank and OECD also project 7.1%. The IMF's 7% is slightly more conservative. These differences matter for rate expectations — a higher growth forecast could justify more rate hikes.
On the rupee, the IMF's upgrade did not prevent the currency from falling. The rupee opened 60 paise higher at 95.17 on Tuesday after the RBI announced fresh measures to curb dollar demand, but that rally faded. The currency closed at 96.78, near its record low of 96.86.
What to Watch Next
The next key trigger is the RBI's monetary policy meeting in December. If inflation stays above 5%, another rate hike is possible. The RBI's next inflation data release is due in November, and any surprise above 5.5% could pressure the rupee further.
For USD/INR traders, the immediate support level is the record low of 96.86. A break below that could open the door to 97.50. But be cautious — the RBI has shown it can intervene to curb volatility.
For gold traders, watch the US Federal Reserve's next meeting. A hawkish Fed would strengthen the dollar and pressure gold, while a dovish stance could boost bullion. The next CPI data from India will also be crucial — if inflation accelerates, gold could find support.
Social Media Buzz and Divergences
On X, market watchers are split. @ShaliniRaoSays notes that yesterday's relief rally was strong but questions whether it can sustain, with GIFT Nifty down 87 points.
@imhiteshmodi highlights daily market triggers, suggesting that one headline can move a stock. @NostraWealth points to a weak opening signal for GIFT Nifty and moderating FII selling.
These posts reflect a cautious sentiment. The IMF's upgrade is positive, but traders are focused on the rupee's slide and foreign outflows. The divergence between the growth story and the currency's weakness is the key debate.
Bottom Line for Traders
The IMF's upgrade is a vote of confidence in India's growth, but it does not change the immediate market dynamics. The rupee is under pressure, inflation is rising, and foreign investors are selling. For traders, the focus should be on the RBI's next move and the inflation data.
If you're holding USD/INR longs, the trend is your friend, but watch for RBI intervention. If you're in gold, the inflation outlook is supportive, but a hawkish Fed could cap gains. The next key date is the RBI's policy meeting in December — until then, expect volatility.